- Long-term care comprises a quarter of total Medicaid expenditures in the state
- An expanding population of people age 65 and older is driving up the cost of care
- Irrevocable trusts allow affluent families to qualify for taxpayer-funded long-term care, undermining Medicaid’s intended purpose and shifting costs to taxpayers
Medicaid Asset Protection Trusts (MAPTs) are increasingly being used by affluent families to shield wealth and shift the cost of long-term care onto taxpayers. Instead of drawing down their resources, households with substantial assets can qualify for Medicaid-funded nursing home care, preserving estates that run into the millions.
Long-term care is undeniably expensive, but Medicaid was never intended to cover those costs for well-to-do families. That mission drift is especially concerning as the population grows older and the demand for care accelerates in the years ahead.
As more baby boomers retire, the percentage of North Carolinians age 65 or older will continue to rise — from 16.5 percent in 2020 to 18.4 percent in 2025 to a projected 19.8 percent in 2030.
At the same time, Medicaid expansion is already straining the federal government’s unstable finances and North Carolina’s health care system, leaving fewer resources for the vulnerable populations it was meant to serve.
Long-term care costs are rising sharply. Nursing home care averages well over $100,000 annually. Allowing affluent families to shift these costs onto taxpayers is morally questionable and fiscally unsustainable.
Medicaid Long-Term Services and Supports
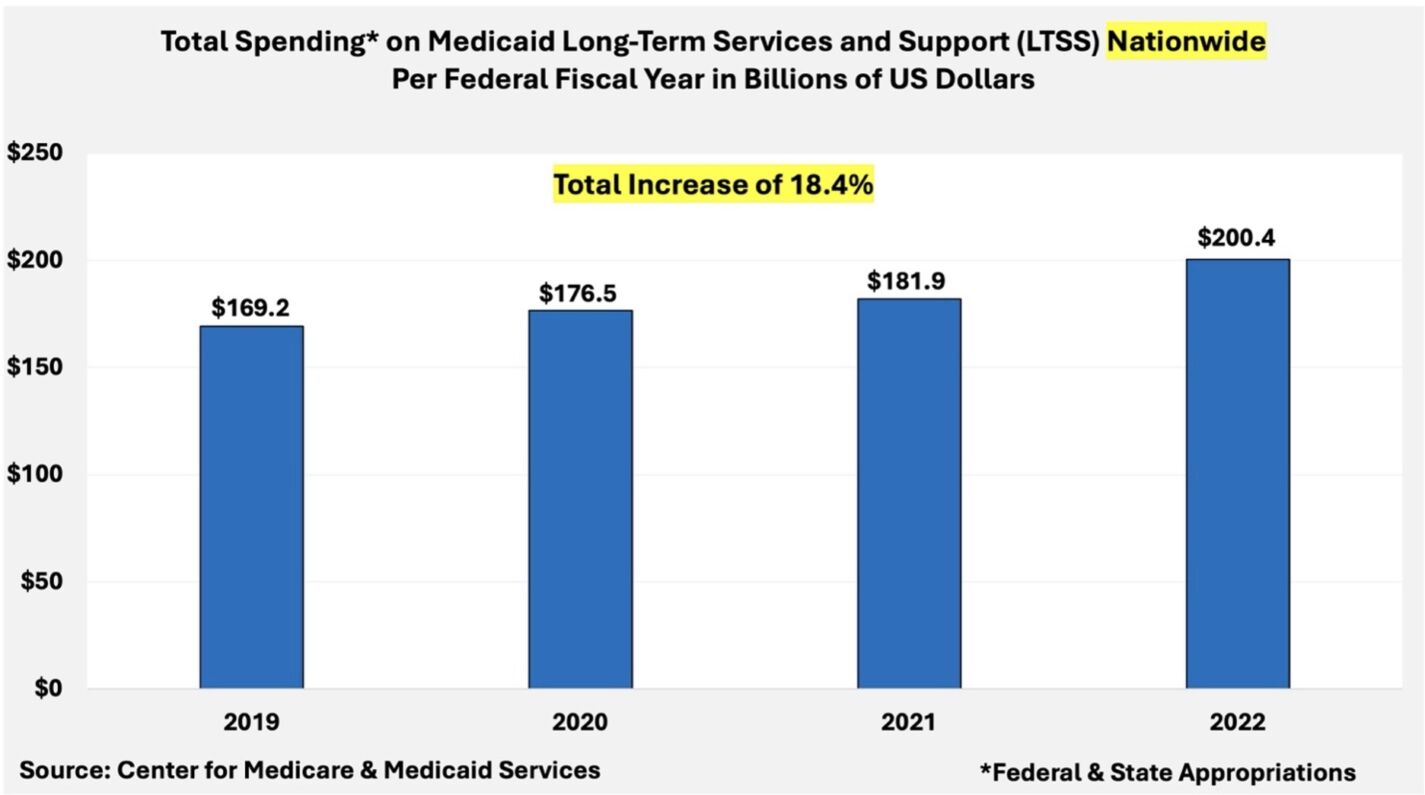
Medicaid Long-Term Services and Supports (LTSS) provides taxpayer-funded care in nursing homes, assisted living facilities, and at home. In recent years, this part of the program has grown increasingly expensive, driven by rising care costs and the growing number of applicants needing long-term support. From federal fiscal year (FY) 2019 to FY 2022, nationwide Medicaid LTSS spending grew from $169.2 billion to $200.4 billion — an 18.4 percent increase.
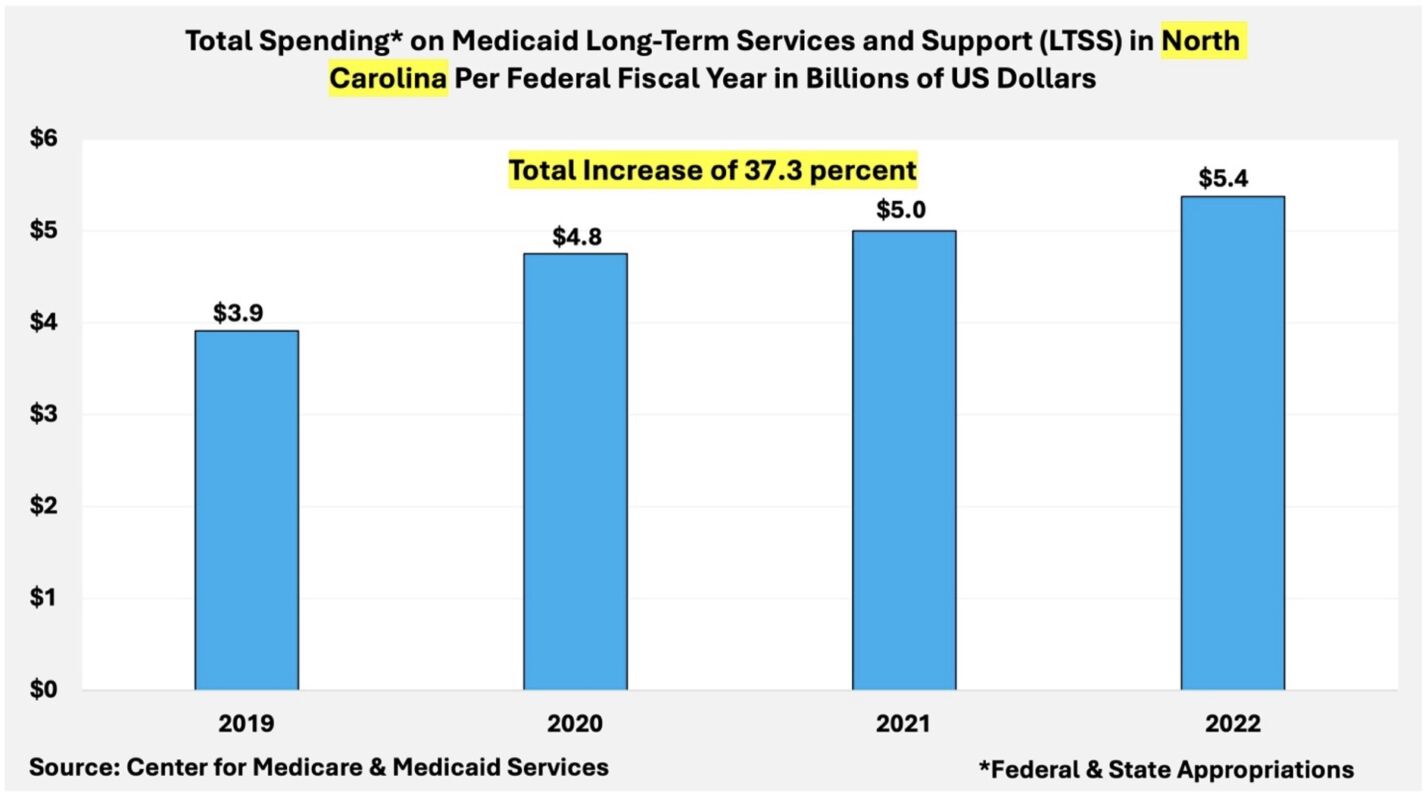
In North Carolina, the trend has been even more dramatic. Over the same period, Medicaid LTSS spending jumped from $3.9 billion to $5.4 billion — a 37.3 percent increase. The $5.4 billion represents 25 percent of total spending on Medicaid in 2022.
Medicaid Asset Protection Trusts
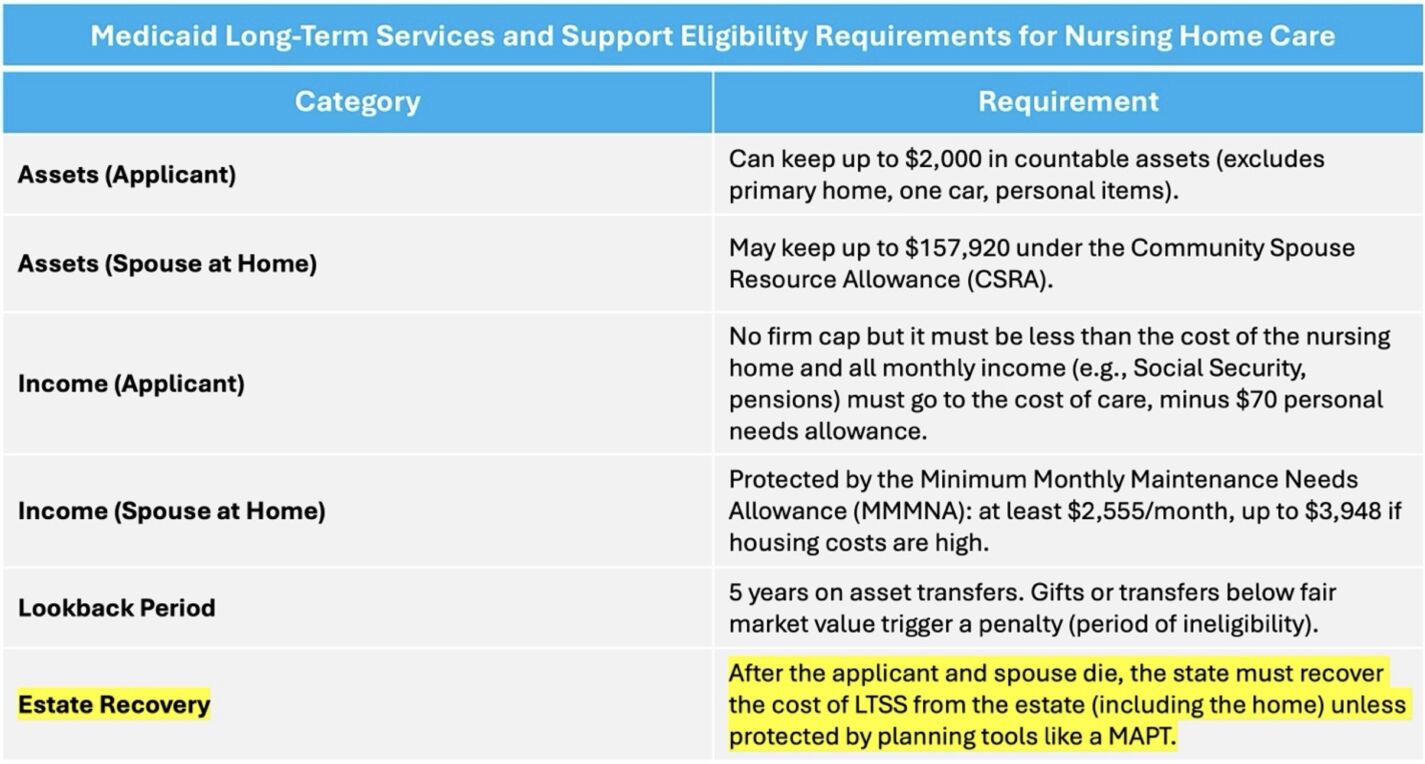
A Medicaid Asset Protection Trust (MAPT) is an irrevocable trust used to move a family’s wealth out of their estate so that it no longer counts toward Medicaid’s strict asset limits. It works by reducing their countable assets through transfers, such as placing a home or investments into a MAPT, but it must be done at least five years before applying for long-term care coverage. With a MAPT, affluent individuals can qualify for Medicaid while preserving their assets for their heirs.
Assets not placed in a MAPT remain part of the estate and are subject to Medicaid estate recovery after both the family member in long-term care and spouse have passed away.
To see how Medicaid planning works in practice, consider a hypothetical married couple who are both 70 years old, have a net worth of $2.3 million, but know the husband will eventually need nursing home care. The couple’s goal is to preserve as much of their wealth as possible for their children by shifting the high cost of the husband’s nursing home care onto taxpayers through Medicaid planning strategies.

Following the advice of an elder law attorney, they establish a MAPT and purchase a Medicaid-compliant annuity to achieve this outcome.
First, the couple transfers their $800,000 home and $700,000 in investments into a MAPT, removing those assets from their estate so that they no longer count toward Medicaid eligibility. They keep $800,000 liquid until the husband eventually needs nursing home care.
At that point, they convert $650,000 into a Medicaid-compliant annuity that pays the wife $4,500 monthly. The other $150,000 they keep in her name under the Community Spouse Resource Allowance. With those steps, the husband’s $4,000 monthly income from Social Security goes directly to the nursing home, while taxpayers cover the balance of his $9,000 nursing home monthly bill ($5,000).
Now, let’s say the husband lives in the care facility for ten years until he passes away. At that point, the couple will have successfully shifted roughly $600,000 in long-term care costs onto taxpayers while preserving about $1.5 million in assets for their children.

Policy recommendations
Medicaid was created as a safety net for the vulnerable, not a vehicle for affluent families to protect inheritances at taxpayers’ expense. Yet through utilizing MAPTs, families with millions in assets can qualify for taxpayer-funded long-term care, while those who don’t often lose their homes to estate recovery.
To address this, lawmakers should take three steps:
- First, reinstate and expand North Carolina’s long-term care insurance tax credit by covering 100 percent of premiums, up to $3,000 per year, giving families a powerful incentive to prepare for their care needs rather than relying on Medicaid.
- Second, strengthen state-level oversight of trust transfers, ensuring that MAPTs and other tools used to shield wealth are subject to greater scrutiny.
- Third, call on Congress to extend the lookback period beyond five years, which would reduce families’ ability to game the system with transfers.
Medicaid LTSS eligibility reform is not about opposing inheritance but about fiscal responsibility and fairness. Taxpayers should not be asked to underwrite the long-term care costs of families with the means to pay.