In 2022, Governor Cooper issued an executive order to raise the number of registered zero-emission vehicles (ZEVs) in the state to 1.25 million by 2030. ZEVs include electric vehicles (EVs) and plug-in hybrids (PHEVs). While the executive order lacks any legal enforcement, it signals increased central planning for ZEVs.
In 2023, annual registration fees were set at $140.25 for EVs and $38.75 for PHEVs, with increases in January 2024 to $180 and $90 and again in July to $214.50 and $107.25. Despite these hikes, the fees remain lower than the annual motor fuels tax revenue from the average driver of an internal combustion engine (ICE) vehicle. If Cooper’s goal of 1.25 million ZEVs is met, it will create an annual funding gap for roads and highways of tens of millions of dollars.
North Carolina Transportation Funding
North Carolina’s Department of Transportation (NCDOT) uses the Highway and Highway Trust Funds for road construction and maintenance. In fiscal year (FY) 2023, the combined revenue of the funds was $7.32 billion, 72 percent of which came from state taxpayers. The state motor fuels tax was the largest source, contributing 36 percent of total revenue.
The federal government provided 28 percent of the revenue. The federally sourced revenue comes from the federal Highway Trust Fund (HTF), most of which is funded through national taxes on gasoline and diesel of $0.184 and $0.244 per gallon, respectively.
Combining state and federal tax revenues, over half of North Carolina’s transportation funding comes from motor fuel taxes.

Moreover, in February 2024, the Congressional Budget Office (CBO) projected that the federal HTF will be insolvent by 2028, mainly due to an anticipated rise in ZEV usage. Notably, the federal government has not raised gasoline and diesel tax rates since 1993 and does not impose registration fees on ZEVs.
Motor Fuels
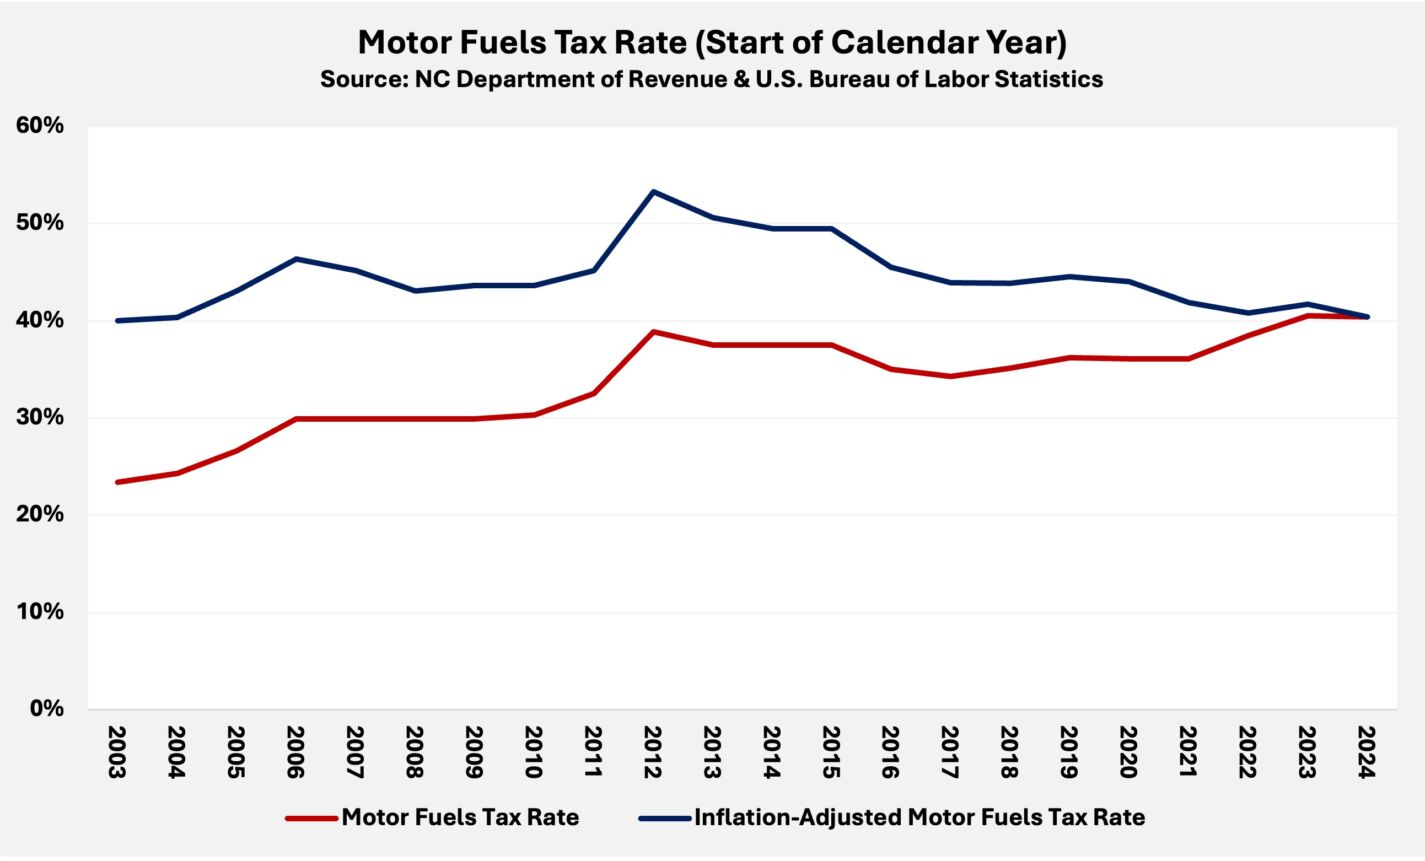
The motor fuels tax rate in North Carolina applies to gasoline and diesel. Since 2003, it has increased from $0.234 to $0.404 per gallon. However, after adjusting for inflation, the tax rate has remained relatively flat.
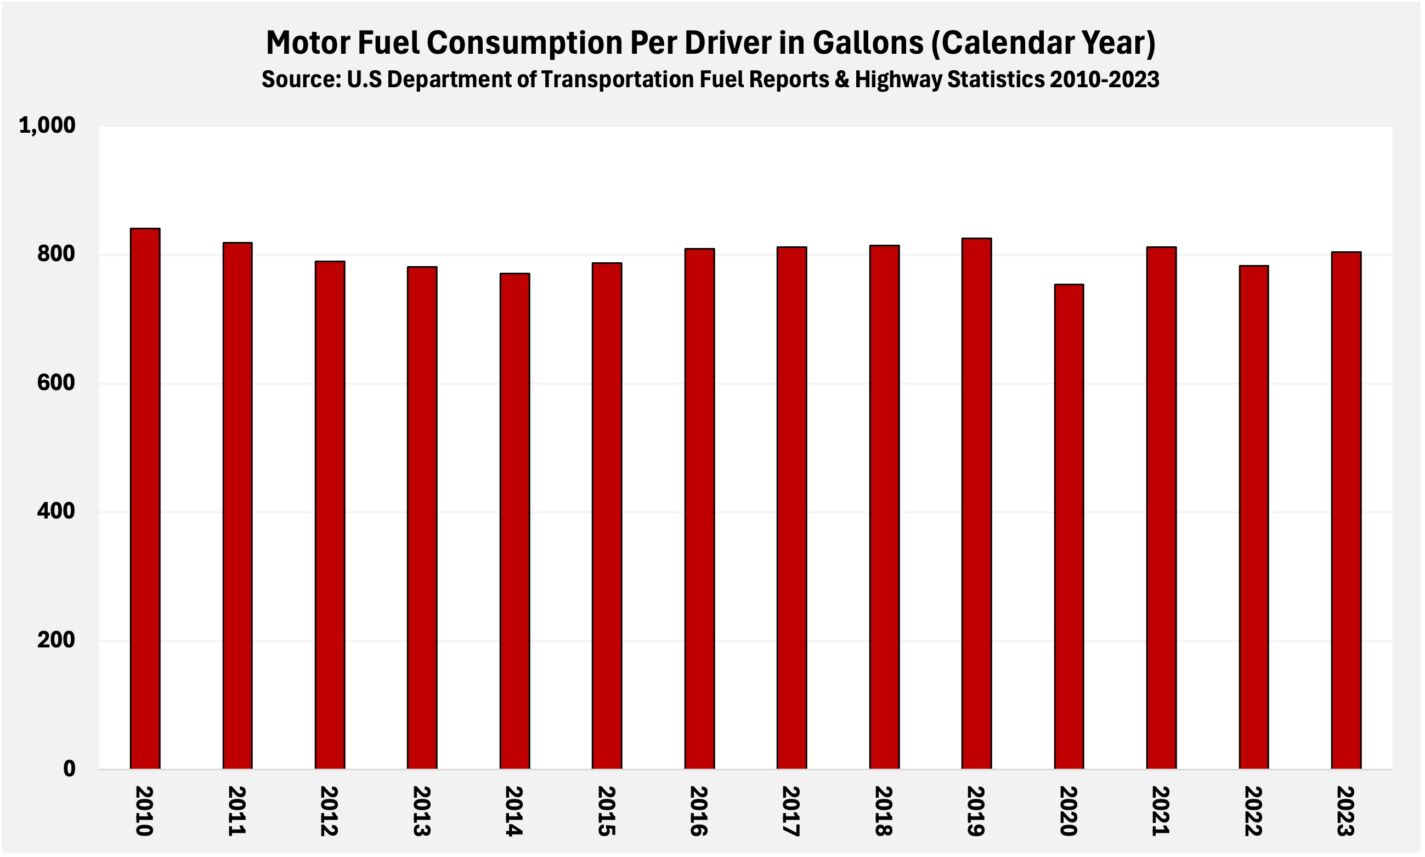
Traditionally, due to a lack of substitutes, motor fuel consumption per licensed driver in the state has varied little from year to year. In 2023, 805 gallons of motor fuel per licensed driver were sold in the state, slightly more than the annual average since 2010 of 800 gallons.
Since 2003, inflation-adjusted annual state tax revenue from motor fuels has risen from $1.98 billion to $2.70 billion, or a 36 percent increase. However, as progressive policymakers push drivers to transition from ICE vehicles to ZEVs, this revenue source is expected to decline.

Zero-Emission Vehicles
From 2016 to 2023, ZEVs increased from less than 0.1 percent of all registered vehicles in the state to approximately 1.1 percent. If Cooper’s 2030 target of 1.25 million ZEVs is accomplished, this figure will rise to 14 percent, requiring a twelvefold increase in ZEVs in just seven years.

It is essential to point out that the prospect of Cooper’s unrealistic goal being attained is unlikely for the following reasons:
- Many Americans do not view ZEVs as legitimate substitutes for ICE vehicles. In a recent Gallup poll, when asked about electric vehicles, 48 percent of respondents were not interested in purchasing one.
- ZEVs are expensive compared to ICE vehicles. Even after applying tax credits, the average price of a new ZEV exceeds that of an ICE vehicle by more than 40 percent.
Nonetheless, every new ZEV in the state generates less tax revenue than ICE vehicles, but causes equal or greater damage to our roads.
In the model below, I estimate the loss in state tax revenue per EV and PHEV. The average driver of an ICE vehicle generates approximately $266.71 in annual motor fuels tax revenue for the state. This exceeds the revenue generated by an EV driver by $52.21 and the typical PHEV driver by $26.10.
Assuming Cooper’s goal is met, and the current share of EVs within ZEVs is constant (74.8 percent), the total loss to the state in tax revenue would be $57.02 million annually at the current fees and tax rate.

Policy Recommendation
In addition to a potential sizeable shift to ZEVs, traditional ICE vehicles continue to become more fuel-efficient. Fewer trips to the pump means less revenue produced by a fuel tax. Even if Cooper’s recommended ZEV goals are not met, changing vehicle technology requires lawmakers to reconsider how NCDOT is funded.
To ensure a reliable and sufficient revenue stream for roads and highways, North Carolina legislators should consider replacing the ZEV fees and the motor fuels tax with a vehicle miles traveled (VMT) tax, also known as a mileage-based user fee (MBUF). A VMT tax charges drivers per mile traveled annually, applying equally to all light-duty vehicles, regardless of fuel type. This directly links road usage costs to actual mileage.
By implementing a uniform rate, a VMT tax enhances fairness in the tax code and addresses the revenue shortfall from insufficient ZEV fees. Additionally, it offers a more stable revenue source than the motor fuels tax, which can decline with increased fuel efficiency in ICE vehicles.
While some suggest using technology to track road usage, this level of oversight is unnecessary. Odometer readings taken during annual vehicle inspections can provide a sufficient method for calculating miles traveled.
To generate revenue similar to the current revenue collected from an ICE vehicle, the starting VMT tax rate should be $0.0178 per mile, which would generate roughly $266.29 annually per driver. To ensure long-term solvency, the VMT tax rate should be adjusted for inflation during each biennial budget process.
North Carolina’s current funding mechanism for transportation infrastructure has been in place for decades. To reflect changing vehicle technology and ensure sufficient revenue moving forward, North Carolina should consider a new method for providing for our roads and highways.


