Introduction
State government is the largest employer in North Carolina, with more than 327,000 full-time-equivalent positions. The average age of a North Carolina state government employee is 47. Attracting and keeping employees is a constant challenge, however. Benefits beyond salary have traditionally been a factor in the desirability of government jobs. In 2023, state employees received benefits averaging $39,754 in addition to their average salary of $62,997. In other words, taxpayers spend more than $102,000 per year for each state government employee.
The 2023 total compensation figure marked a 74 percent increase over 2008 and a 23 percent increase in just the past three years.
The fastest-growing component of employee compensation is the state payment for pensions and health benefits. The cost to taxpayers of providing these two benefits increased by a whopping 219 percent from 2008 to 2023, more than tripling from $7,318 to $23,319.
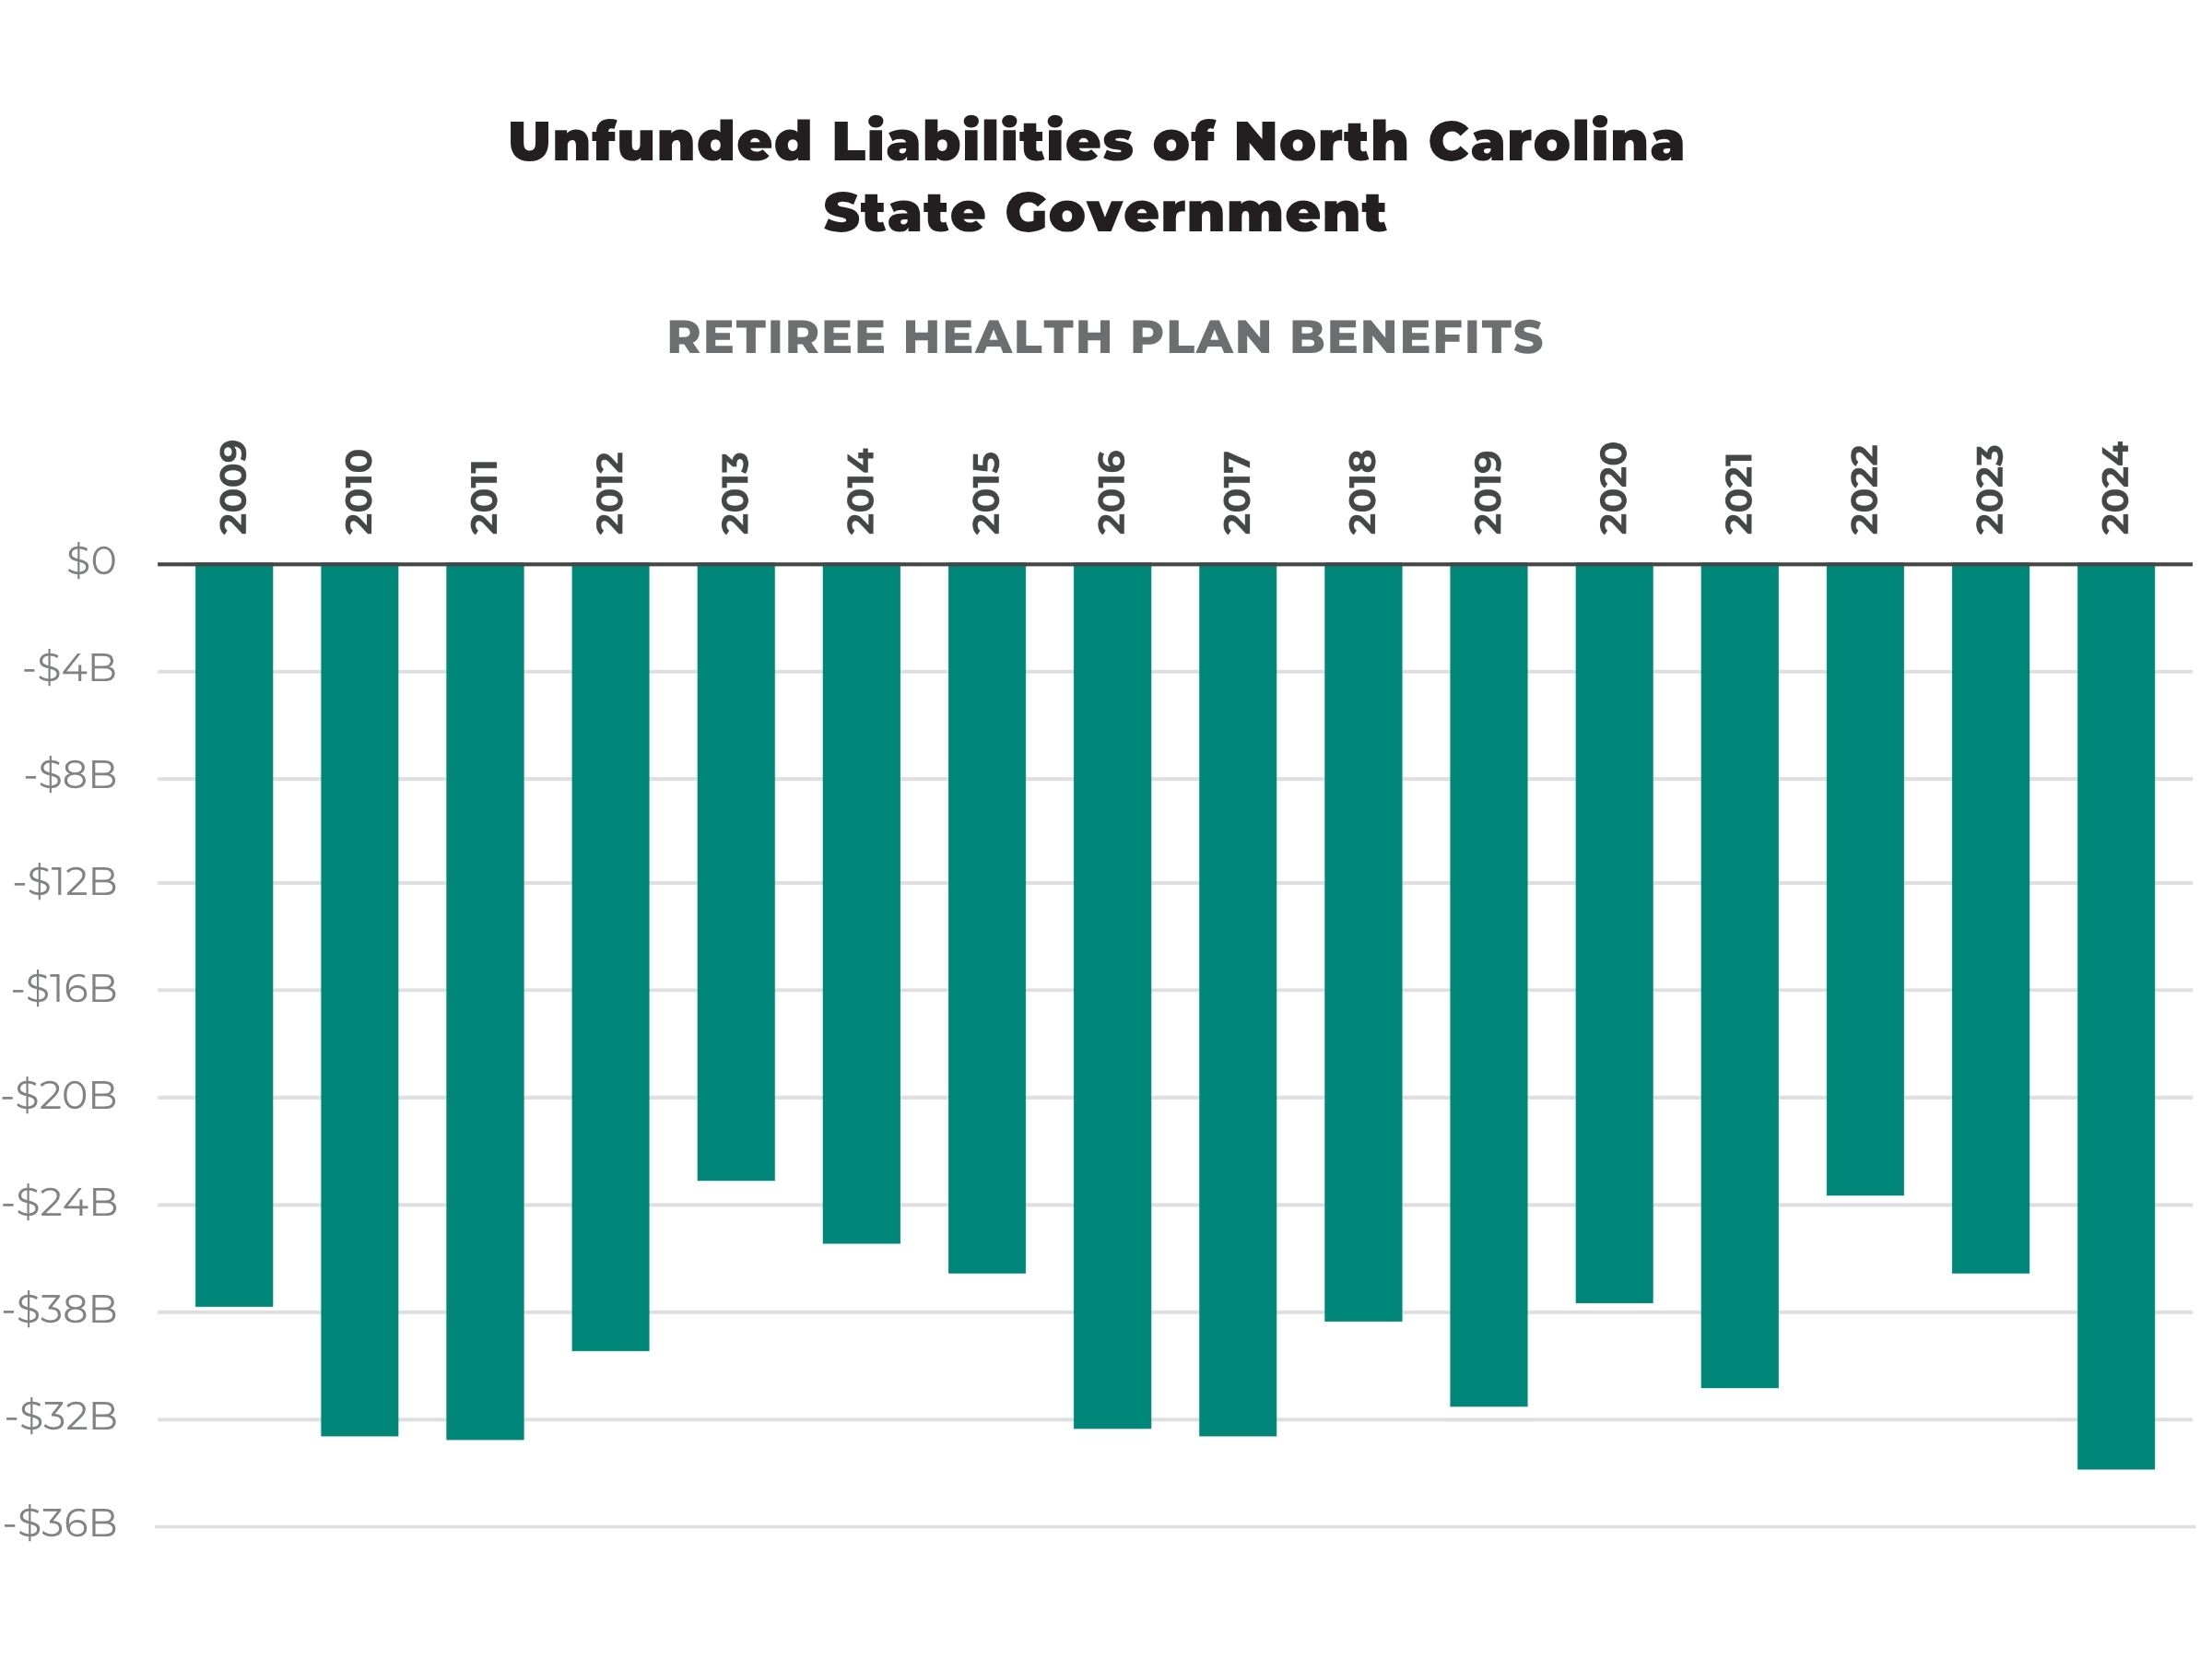
Retired state employees currently receive generous health insurance at no cost, and they have the option of upgrading to even more generous coverage for a small monthly premium. In 2024, the unfunded liability for retiree health-plan benefits totaled $34 billion. North Carolina state employees who started work after Dec. 31, 2020, however, are not eligible to participate in the State Health Plan after retirement, a move that remedies the retiree health-care cost liability well into the future. Still, the daunting liability of the next several decades must be addressed.
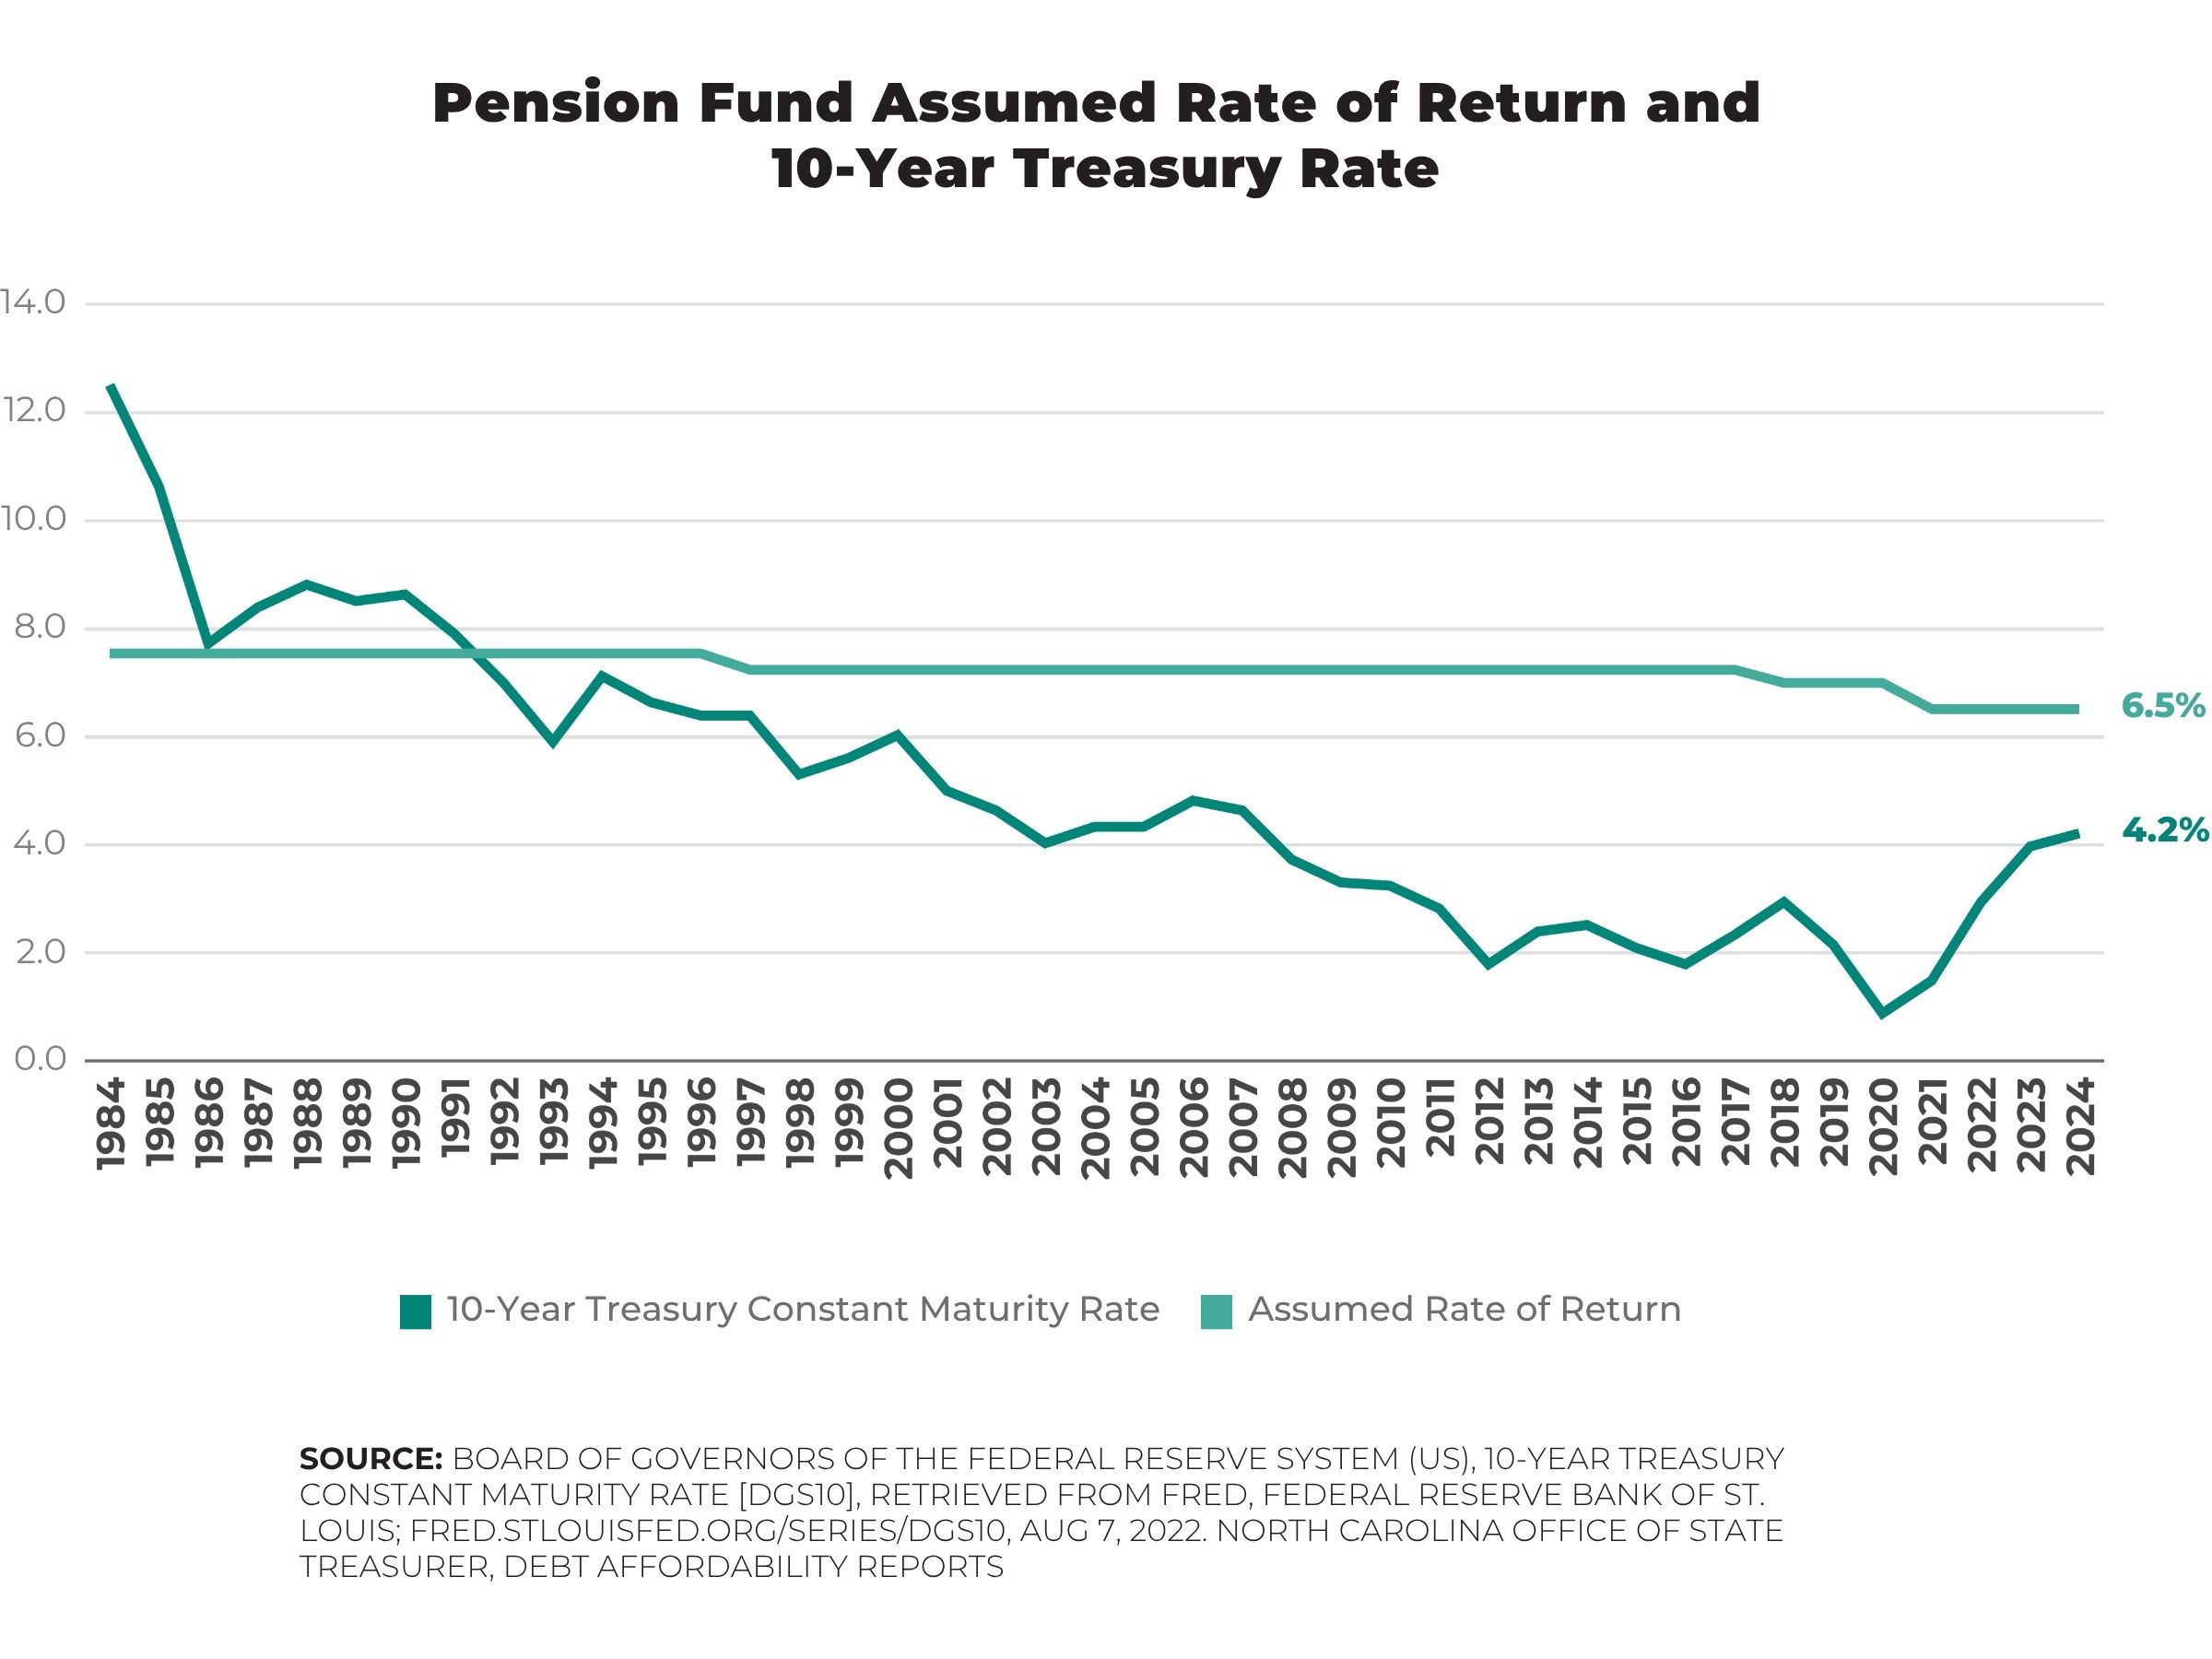
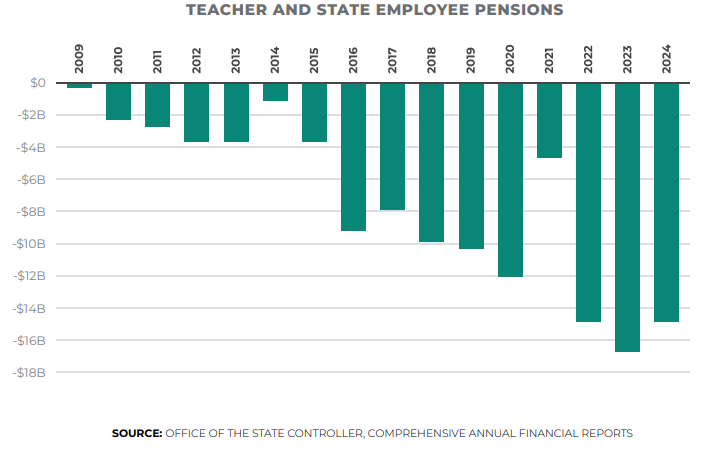
Retirees also receive pension payments based on their length of service and their last three years of salary. The largest pension system, the Teachers’ and State Employees’ Retirement system (TSERS), has assets valued at more than $86 billion yet owes current and future retired teachers and state employees $101 billion, thereby creating an unfunded pension liability of nearly $15 billion. Investments have fallen short of the assumed rate of return, even though former state treasurers took advantage of greater latitude to invest in hedge funds and other nontraditional assets. Significant market downturns during the 2020 Covid lockdowns and the 2022 inflation scare have put the pension fund further behind pace.
Former State Treasurer Dale Folwell pared back the assumed rate of return for pension assets from 7.20 percent in 2018 to 6.5 percent in 2021, bringing expectations closer to reality.
North Carolina’s pension system guarantees a defined level of monthly payments to retired state employees for life. If there were not enough money available to cover these payments, the state would need either to raise taxes or to cut spending in other areas. The risk to employees is that the liability, left unaddressed, would be so great that the state would need to reduce the monthly pension payments. As municipal bankruptcies around the country have demonstrated, unfunded liabilities can lead governments to raise taxes or to cut or eliminate benefits without warning.
To reduce the risks to both taxpayers and retirees, in 2017, Michigan switched from traditional defined-benefit pensions to defined-contribution retirement plans, which create individual accounts for employees to manage with funds that they and the state government contribute during their careers. There is no guaranteed payout and no hidden risk to taxpayers with defined contribution plans.
Key Facts
- Employer contributions for state pension and health benefits totaled more than $23,000 per employee in 2023, an increase of 219 percent from 2008. A higher cost for required benefits means less money for salaries.
- Unfunded liabilities for state pensions and retiree health benefits total nearly $50 billion.
- The state eliminated free health benefits upon retirement for employees who began their employment after Dec. 31, 2020.
- State pension investments have not met the assumed rate of return over the past 20 years, even with the recently reduced rate of 6.5 percent.
Recommendations
1. Contribute the actuarially required amount to meet future state health-plan obligations.
Unfunded liabilities could harm future retirees, taxpayers, and the state’s AAA bond rating. An annual appropriation needs to be established for both the pension and health plans until each is at least 95 percent funded (the pension fund is currently 85 percent funded — albeit with a 6.5 percent assumed rate of return that is likely still too high — and retiree health benefits are funded at only 10 percent).
2. Continue reducing investment return expectations for pensions.
Setting a lower bar for investment returns will allow pension managers to stop chasing riskier investments in the hope of meeting overly ambitious targets. It will also produce more realistic liability figures, prompting higher annual required contributions.
3. Take Additional Steps to Reduce Current Healthplan Costs and Long-Term Liability.
Several services help people save money on health costs. Making them available to employees covered by the State Health Plan can improve the plan’s finances. Asking retirees to contribute a small monthly premium for basic coverage, and slightly higher premiums for current employees, would provide some minimal relief for the overwhelmed state health plan.
4. Transition to Defined-Contribution Pension Alternatives for Both New and Current Employees.
New teachers, corrections officers, and other state employees often do not reach the five years of service needed to vest in the pension system. They should have better choices, and those choices should be open to longer-service employees as well. Employees enrolled in 401(k)-style defined-contribution plans immediately have control over their retirement contributions, instead of having to wait to be vested in their pension. Moreover, defined-contribution plans remove the risk to taxpayers of having to pay for massive — and growing — pension liabilities.
5. Increase Transparency of the Pension Plan and Other Employee Benefit Plans.
Financial statements for these accounts need to be available for review in a convenient place, preferably an easily accessible website. Finances should be considered a priority when evaluating the state’s fiscal situation. State employees should be able to see the value of their benefits and the likelihood of receiving those benefits.