Introduction
For many years, economists and tax policy researchers maintained that North Carolina’s tax system needed a major overhaul. The system was a model of hodgepodge tax policy with high marginal rates on personal and corporate incomes and many exemptions carved out for the favored few. This led to a tax system that generally penalized investment, entrepreneurship, economic growth, and therefore job creation.
The process of improving the tax code began in 2011. A 1 percent temporary increase in sales tax put into effect in 2009 was set to expire. North Carolina Gov. Beverly Perdue was in favor of continuing the higher rate past its expiration date. Ultimately, it was allowed to sunset, but only because of an override of Gov. Perdue’s veto of legislation by the newly elected Republican majority in the North Carolina General Assembly
In 2013, the General Assembly implemented fundamental tax reform, which has become a model for states across the country. From the perspective of economic growth, the two most important improvements were pro-growth reforms in the personal and corporate income taxes. In addition, lawmakers also incorporated across-the-board tax cuts that would benefit most households in all income groups. The deliberative process that led to these changes was thoughtful and, in large part, ignored the kind of special-interest pleadings that typically plague such reform efforts.
Subsequent, smaller reforms have continued to improve North Carolina’s tax code, so much so that the Tax Foundation ranked North Carolina’s business tax climate as 12th best in the nation in 2025. In 2012, just prior to the major 2013 reforms, North Carolina ranked seventh worst in this index.
During the 2021 legislative session, the General Assembly continued its tax-cutting ways when it approved a budget plan including personal income tax cuts, a phaseout of the corporate income tax after 2029, and a simplification of the franchise tax that effectively lowered tax bills. The 2023 budget increased the rate of the personal income tax cuts, reducing the rate to 3.99 percent in 2026, with a path to reach 2.49 percent through 0.5-percentage-point annual increments in years in which certain revenue targets are met.
While this progress is laudable, more improvements should be made. North Carolina’s tax code still has some features that are biased against saving and investment. In particular, by taxing interest and capital gains, the state tax code limits saving and investment, which hinders economic growth. This needs to be remedied. The corporate income tax phaseout should be preserved, and the franchise tax should be eliminated. Meanwhile, the state’s continued use of targeted tax breaks to politically favored corporations should end.
Key Facts
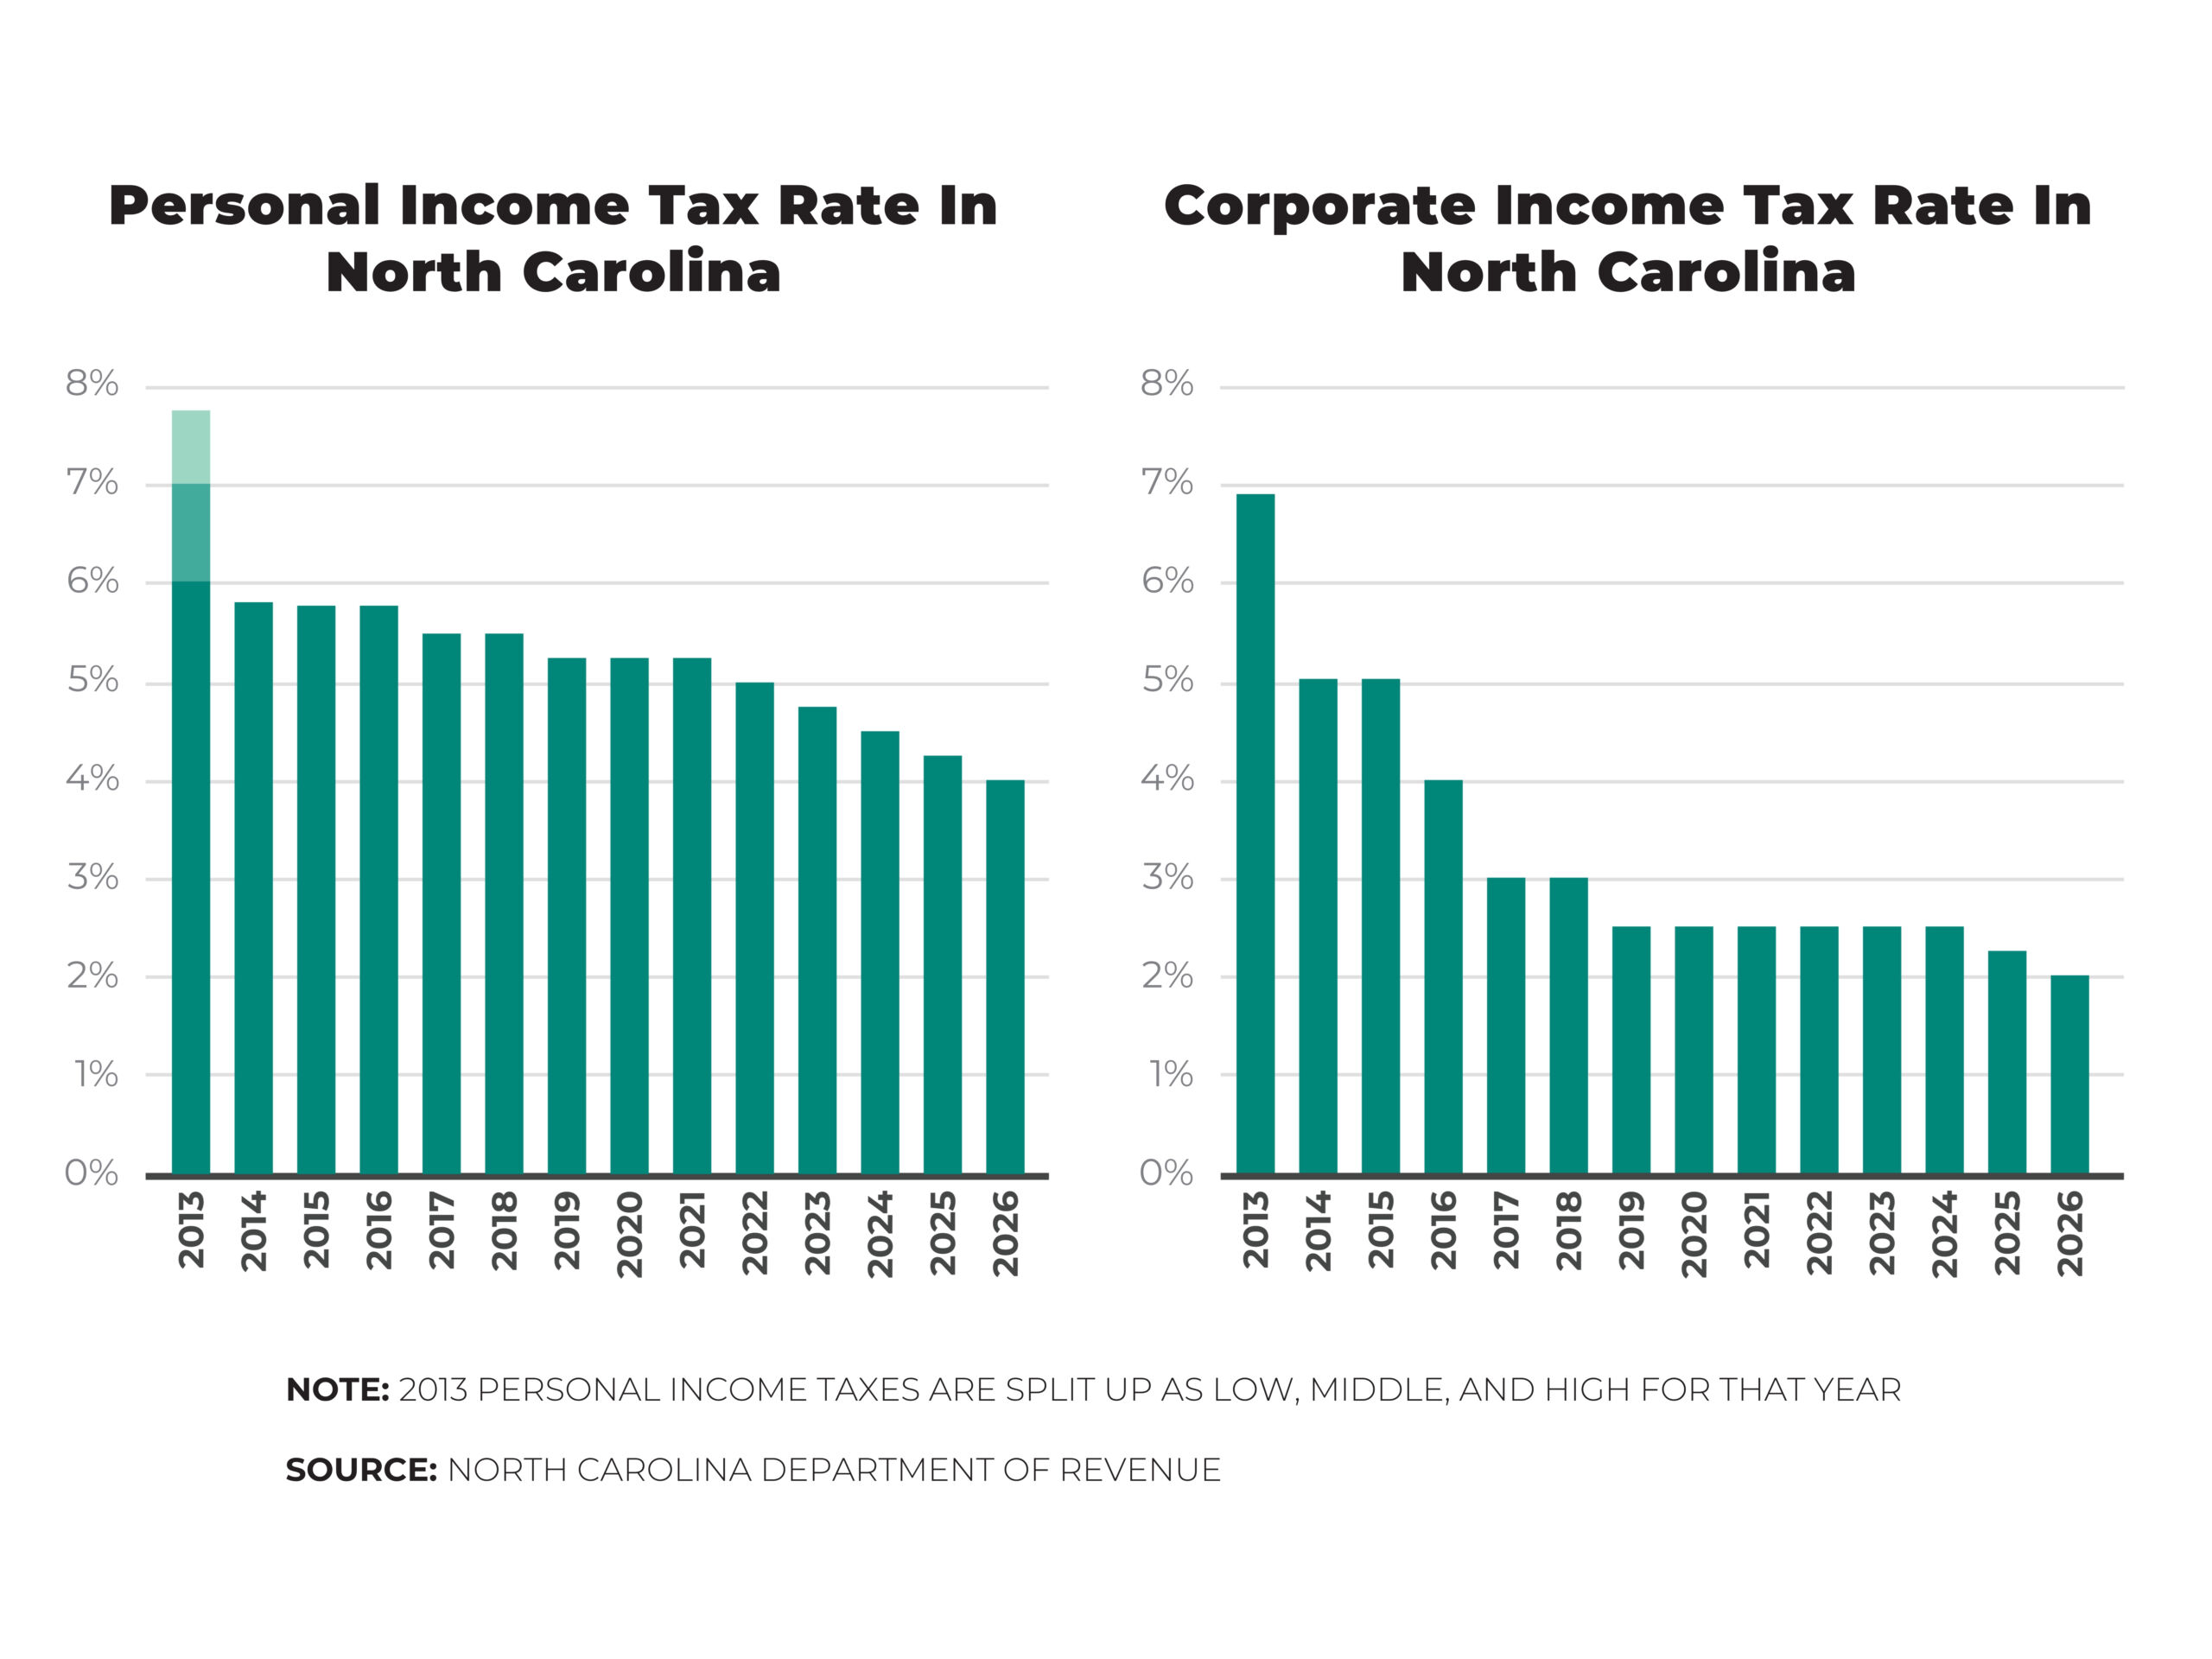
- The 2013 tax reforms replaced a three-rate progressive personal income tax that ranged from 6 percent to 7.75 percent, the highest in the region, with a flat-rate tax of 5.8 percent. This rate was subsequently lowered eight times, arriving at 3.99 percent as of 2026. The rate now has a path to 2.49 percent through 0.5-percentage-point increments, contingent on revenue targets being met.
- In their 2025 biennial budget proposals, the Senate and the House both sought to alter current law on personal income tax rate reductions, but they did so in starkly different manners. The Senate’s proposal recommended removing the revenue targets needed for the rate to fall to 2.99 percent, keeping the target for the reduction to 2.49 percent, then adding two additional target-based cuts, each of 0.25 percentage points, to bring the rate to 1.99 percent. In contrast, the House’s proposal recommended substantially increasing the revenue targets, making future revenue-based personal income tax rate cuts unlikely. As of this report’s publication, lawmakers have yet to reach a compromise on the 2025 biennial budget, largely due to disagreements over personal income tax reform.
- The standard deduction, also known as the “zero tax bracket,” has been dramatically increased from $6,000 prior to the 2013 reforms to $25,500 for a couple filing jointly in 2022. This was a way of building progressivity into what is essentially a flat-rate system.
- The corporate income tax rate has been reduced from 6.9 percent in 2012, the highest in the Southeast, to 2 percent as of 2026, the lowest of any state that taxes corporate income. The 2021 budget included a phaseout of the tax after 2029.
- Business-to-business sales continue to be taxed. Charging sales tax on business-to-business purchases leads to double taxation. The business pays sales tax on the inputs, and the customer pays sales tax again on the final product that includes those taxed inputs.
- North Carolina continues to restrict investment by taxing capital gains. Repealing the capital gains tax would unlock investment, promote entrepreneurship, and foster long-term economic growth.
Recommendations
1. Future tax reform should take into account the personal income tax rate reduction revenue
targets.
Because future reductions in the personal income tax rate below 3.99 percent are contingent on meeting specific revenue targets, any additional tax reforms must be evaluated in light of their potential to reduce revenue and jeopardize rate reductions.
2. Eliminate the franchise tax.
This tax is particularly harmful to wages, investment, and economic growth. The 2023 budget placed a cap on the franchise tax for C-corporations (a cap was passed for S-corporations in the 2017 budget), and legislators should take the next step by eliminating it.
3. Index the “zero tax bracket” to inflation.
The income tax’s standard deduction should be indexed to inflation so that wage increases merely keeping up with inflation (or not rising as fast as inflation) do not get pushed up into the taxable income category.
4. Future reform efforts should focus on excluding savings and investments from the tax base.
This would eliminate the bias against saving, investment, and entrepreneurship that still exists in the tax code. A good first step in this direction would be to eliminate taxation on capital gains or, at the very least, to create a capital gains exclusion. The reduction in revenue to the treasury from reducing or abolishing the capital gains tax should be partially offset by eliminating economic development programs that subsidize certain businesses. (See Economic Growth)
5. Businesses should be allowed to deduct all purchases of capital equipment and land in the year they are incurred, a practice known as expensing.
This approach has been adopted at the federal level and should be applied to North Carolina. North Carolina should make immediate expensing a permanent feature of the state’s tax code to ensure state expensing even if it ends at the federal level.
6. There should be a moratorium on any new expansion of the sales tax base until business-to-business sales are exempted from the tax.
This is a hidden double tax embedded in the system. Businesses are taxed on the materials they purchase, and consumers are taxed on the final products made from the already taxed materials.